Limited 203(k)
For Smaller Renovations and Repairs
Designed for minor remodeling and nonstructural repairs. Eligible borrowers can finance up to $75,000 in rehabilitation costs, subject to program requirements.
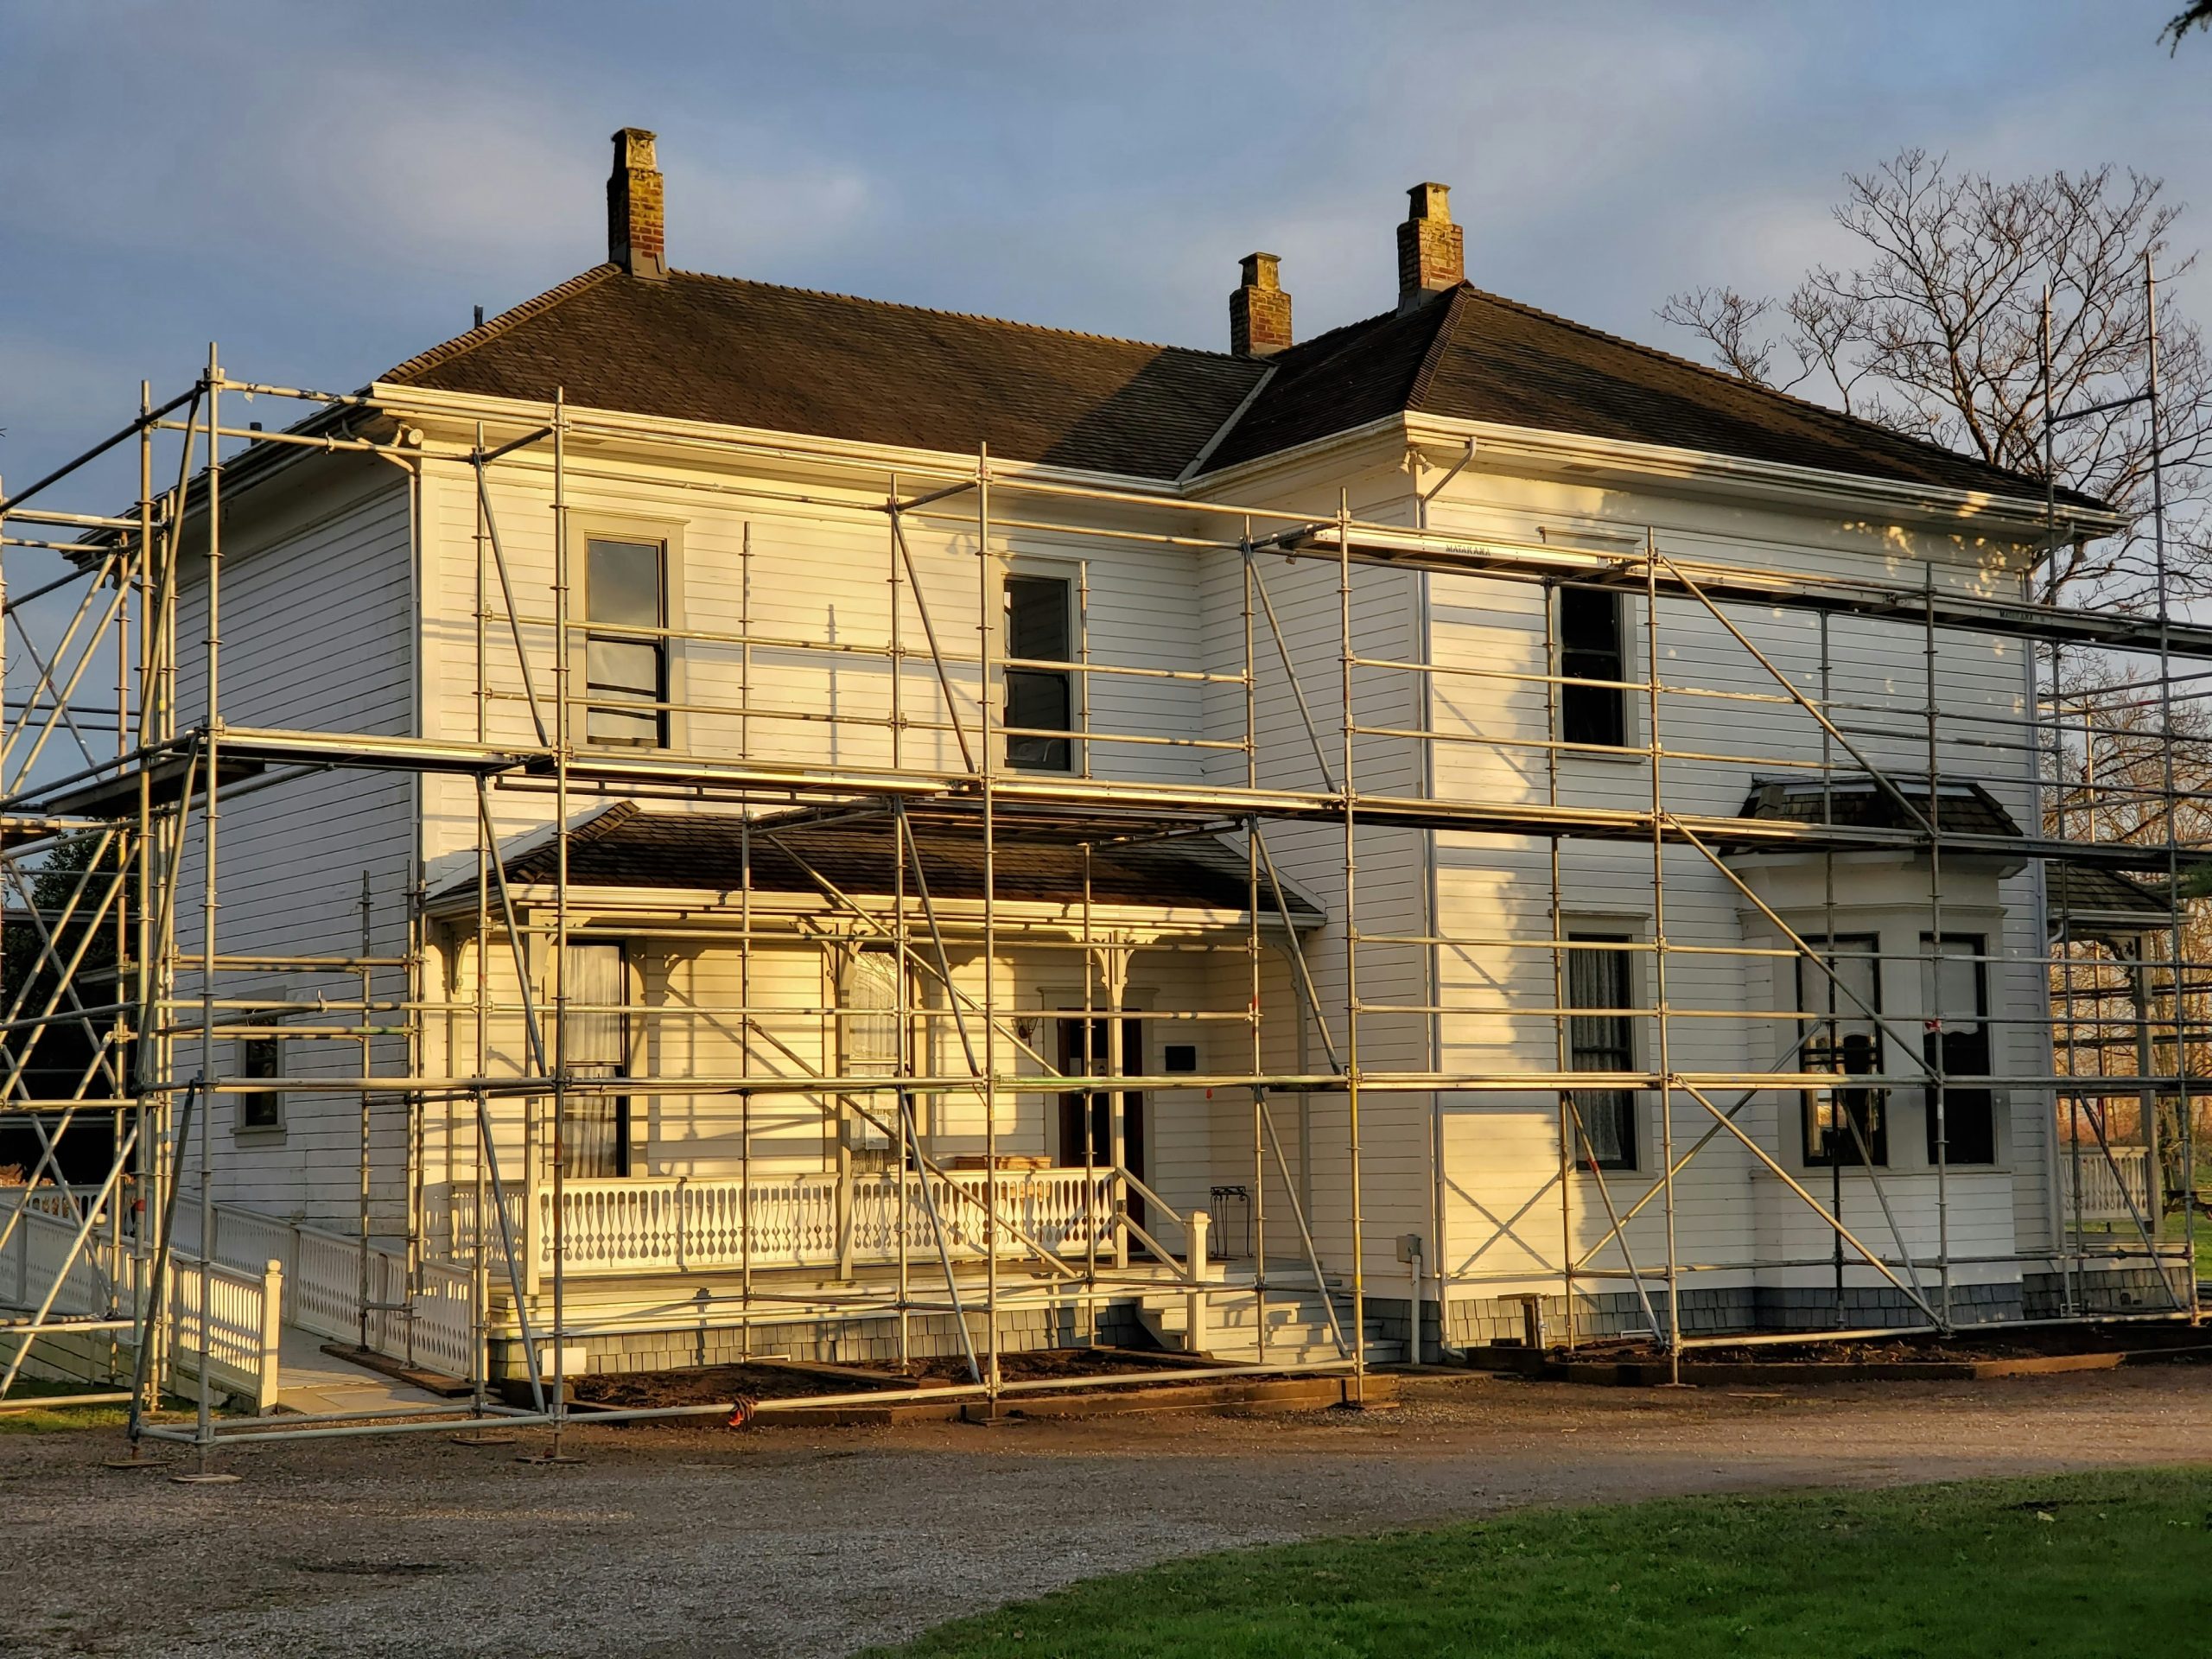
The right home doesn't always come move-in ready. An FHA 203(k) renovation loan can help eligible buyers and homeowners finance both the property and qualifying improvements through a single FHA-insured mortgage.
Instead of purchasing a home and then finding separate financing for renovations, a 203(k) loan allows qualifying repair and improvement costs to be incorporated into the mortgage. The program can be used for an eligible home purchase or refinance.
FHA offers two versions of the program: Limited 203(k) for smaller, nonstructural projects and Standard 203(k) for more extensive rehabilitation.
| Limited 203(k) | Up to $75,000 in eligible rehabilitation costs |
| Standard 203(k) | Designed for major rehabilitation and structural projects |
| Occupancy | Generally owner-occupied eligible properties |
| Minimum Standard Repairs | $5,000 |
| Renovation Funds | Held in a rehabilitation escrow and released as work progresses |
FHA 203(k) offers two renovation financing options depending on the scope of the work.
For Smaller Renovations and Repairs
Designed for minor remodeling and nonstructural repairs. Eligible borrowers can finance up to $75,000 in rehabilitation costs, subject to program requirements.
For Major Renovations
Designed for more extensive rehabilitation, including qualifying structural repairs, additions, and major property improvements. An FHA-approved 203(k) consultant is generally required.
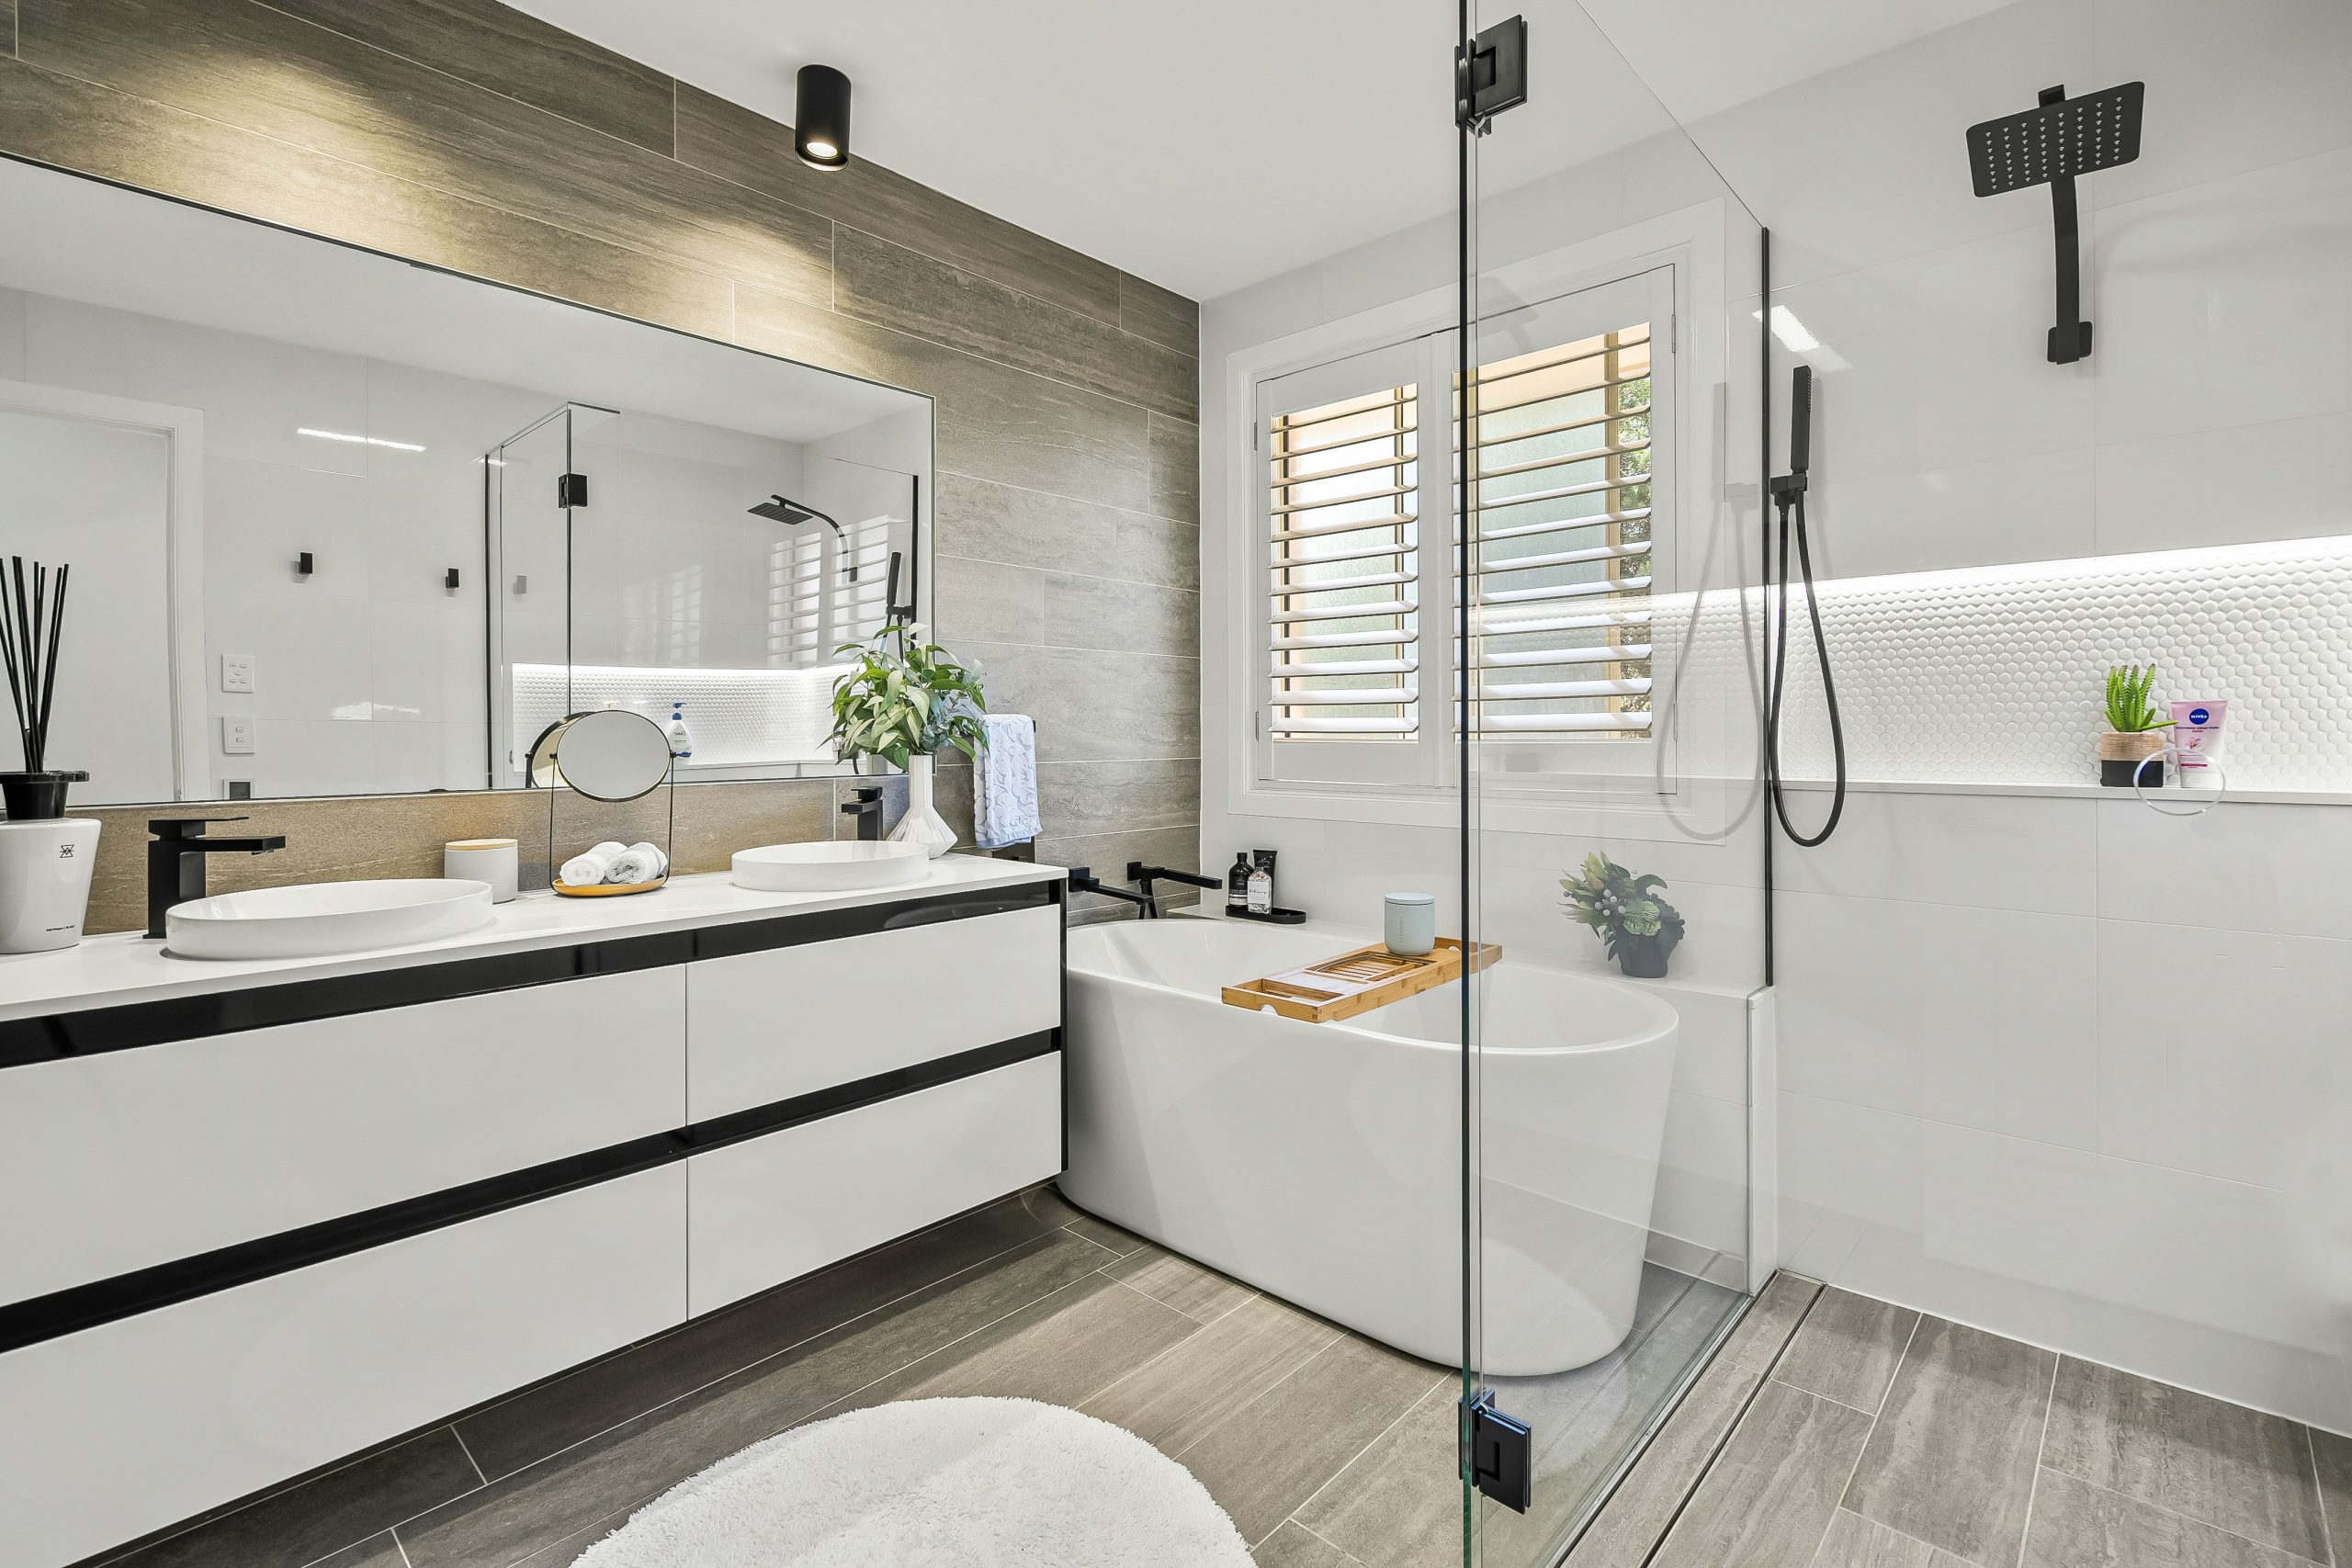
FHA 203(k) financing can cover a wide range of eligible improvements, from kitchens, bathrooms, roofing and flooring to major systems, accessibility upgrades and certain structural repairs.
The property, proposed improvements, contractors and rehabilitation plan are subject to applicable FHA and lender requirements.
Financed rehabilitation funds are generally placed into an escrow account and released as qualifying work is completed.
Limited 203(k) is intended for smaller nonstructural projects, while Standard 203(k) can accommodate major rehabilitation and structural work.
An FHA-approved 203(k) consultant is required for Standard 203(k). Consultant use is generally optional for Limited 203(k).
Explore traditional conventional financing with a variety of down payment and property options.
LEARN MOREExplore programs that may help eligible homebuyers with upfront homeownership costs.
LEARN MOREAn FHA 203(k) is an FHA-insured mortgage that allows eligible borrowers to finance the purchase or refinance of a property along with qualifying renovation and repair costs through a single mortgage.
Limited 203(k) is intended for minor remodeling and nonstructural repairs and currently allows up to $75,000 in eligible rehabilitation costs. Standard 203(k) is designed for more extensive rehabilitation, including structural projects, and requires an FHA-approved 203(k) consultant.
For current eligible transactions, Limited 203(k) allows up to $75,000 in total rehabilitation costs.
Yes, qualifying structural repairs and major rehabilitation may be eligible under the Standard 203(k) program. Limited 203(k) is intended for nonstructural repairs and improvements.
The home you want may just need the right improvements. Let our team help you determine whether an FHA 203(k) renovation loan fits your property, project and financing goals.